Here's the uncomfortable part: most owners have the majority of their net worth tied up in a company they can't easily price. Unlike public stocks, there's no ticker to check.
That's where Enterprise Value (EV) comes in. It's the standard metric buyers, private equity firms, and M&A advisors use to price an acquisition, not book value, not a gut-feel number, and not what you think you deserve. This article breaks down the EV formula, how it differs for private versus public companies, what moves your multiple, and the ceiling a buyer's own funding puts on the number.
Key Takeaways
- Enterprise Value = Equity Value + Total Debt + Preferred Stock + Minority Interest − Cash
- Private companies estimate EV with an EBITDA multiple, not market capitalization
- What a founder takes home is equity value, not EV: equity value comes after debt and cash adjustments
- Your multiple turns on customer concentration, growth, margins, and management depth, not industry averages alone
- EV also has a funding ceiling: senior debt typically covers only 2.0x to 3.0x EBITDA, and the rest has to be equity
What Is Enterprise Value and Why It Matters for Private Companies
Think of Enterprise Value like buying a house with an outstanding mortgage. The total cost of ownership is the equity check you write plus the debt that comes with the property.
EV works the same way: it is the theoretical total price to acquire a business, including the debt a buyer assumes, minus cash on the balance sheet that offsets the purchase price.
Wall Street Prep describes EV as a capital-structure-neutral measure of operating value. It reflects what the business is worth to all stakeholders (shareholders, lenders, and preferred holders alike), not just common equity.
Public companies calculate EV starting from market capitalization, since share price times shares outstanding gives you an instant equity value. Private companies don't have that luxury. There's no daily stock quote for a $30 million distribution company in New Hampshire.
That means private company EV has to be estimated, usually through:
- An EBITDA multiple
- A discounted cash flow model
- Comparable transaction data
This is the figure institutional buyers and PE firms use to compare deal opportunities on an apples-to-apples basis, regardless of how each target is capitalized.

The Enterprise Value Formula: How It's Calculated
The standard formula:
Enterprise Value = Equity Value + Total Debt + Preferred Stock + Minority Interest − Cash and Cash Equivalents
Here’s what each component does in a deal:
- Total Debt: assumed or repaid by the buyer, so it adds to acquisition cost
- Cash and Cash Equivalents: reduces the effective price, since the buyer inherits that cash
- Preferred Stock: another layer of claims on the business ahead of common equity
- Minority Interest: ownership stakes held by outside parties in subsidiaries
A Quick Numeric Example
Say two companies both have an equity value of $10 million.
- Company A: $2M debt, $500K cash → EV = $11.5M
- Company B: $6M debt, $200K cash → EV = $15.8M
Same equity value, very different total price tags. This is why founders can't rely on equity value alone when benchmarking against "what similar businesses sold for."
That gap matters even more for private companies, where there is no market cap to start from. Equity value has to be estimated first through comparable transactions, discounted cash flow analysis, or an EBITDA multiple before the EV formula can be applied. The quality of that equity input depends on real precedent transaction data, not a back-of-the-envelope multiple.
Calculating Enterprise Value Using the EBITDA Multiple Method
Since private companies lack a public share price, the EBITDA multiple has become the industry-standard shortcut. It's simple and defensible because it's grounded in real transaction data.
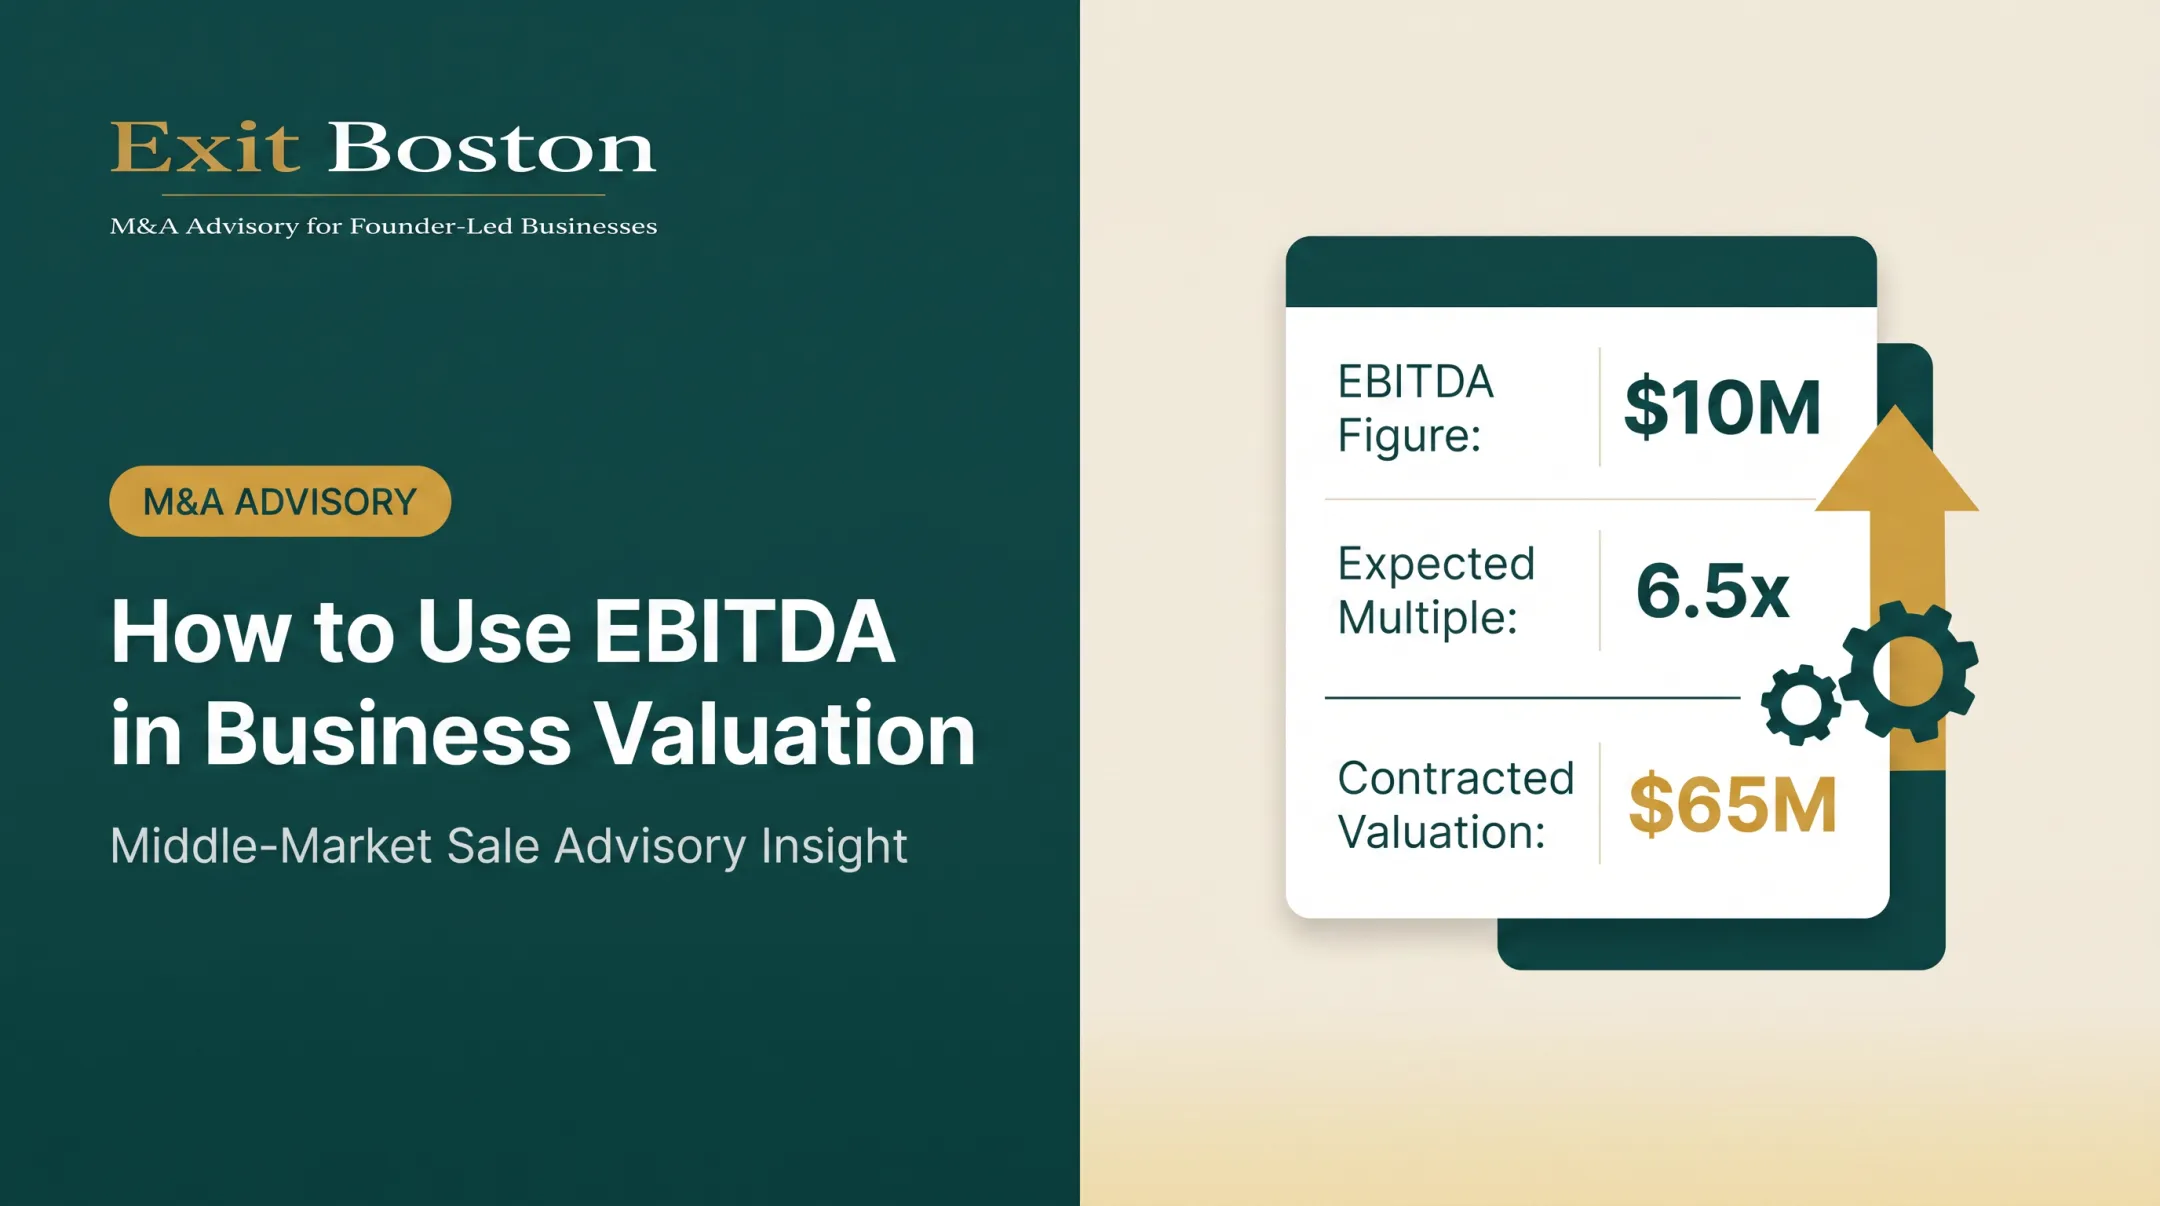
Enterprise Value = Adjusted EBITDA × EBITDA Multiple
What Multiple Range Applies?
Recent GF Data figures on private middle-market transactions show meaningful variation by deal size:
| Total Enterprise Value | Multiple (FY 2024) |
|---|---|
| $10M–$25M | 6.4x |
| $25M–$50M | 6.8x |
| $50M–$100M | 8.3x |
The broader GF Data private M&A universe averaged 7.2x TTM EBITDA in FY 2024, unchanged from 2023. Their Q3 2025 data on PE-sponsored deals shows multiples climbing to 7.5x.
These figures are TEV-based, not revenue-based, so a company's actual deal size (not top-line revenue alone) drives which range applies.

TTM vs. Multi-Year Averaging
Most valuations use trailing twelve months (TTM) EBITDA as the base. But if a business had a volatile year (a one-time customer loss, a pandemic-era spike), averaging the last two to three years often produces a more defensible number.
Why "Adjusted" EBITDA Matters
Raw EBITDA rarely reflects a business's true earning power. Adjustments (add-backs) typically include:
- Owner compensation above or below fair market rate
- Personal expenses run through the business (vehicles, travel, memberships)
- One-time legal, litigation, or restructuring costs
- Non-recurring bonuses or unusual write-offs
Illustrative example: A business reports $2.8M in EBITDA. After normalizing for above-market owner salary ($300K) and a one-time legal settlement ($150K), Adjusted EBITDA rises to $3.25M.
At a 6.5x multiple, that's the difference between a $18.2M EV and a $21.1M EV, nearly $3 million from documentation alone.

Exit Boston applies this same EBITDA-multiple framework when preparing founders for sale or recapitalization, drawing on Steve Vesey's 25 years of business valuation work and Rick McDonald's two-plus decades across 50 to 100 closed middle-market transactions.
Reading Enterprise Value From the Funding Side
Everything above derives EV from earnings. A buyer derives it from the other direction as well, because EV is also the number its funding sources have to add up to. Four layers usually do that work, each with different rights, risks and return expectations: senior debt, subordinated or mezzanine debt, investor equity, and seller rollover equity.
The first layer is capacity-constrained. In middle-market transactions, senior bank debt typically supports 2.0x to 3.0x EBITDA. Apply that to the $3.25 million of adjusted EBITDA above, priced at 6.5x for a $21.1 million enterprise value: senior debt covers roughly $6.5 million to $9.75 million of the price. Every remaining dollar has to come from the sponsor's own equity, from mezzanine capital, or from your rollover.
This is why enterprise value has a ceiling that has nothing to do with your industry's average multiple. Thin debt capacity forces a thicker equity layer, and equity is the most expensive money in the stack, so the same return target now supports a lower price.
Read from this side, the priority list changes. Anything that increases what a lender will underwrite, such as stable margins, contracted forward revenue and consistent monthly reporting, raises the price a buyer can pay without changing the return it needs.
Enterprise Value vs. Equity Value: Understanding the Difference
Here's where founders often get tripped up. EV is not what you pocket at closing.
Most private company sales happen on a cash-free, debt-free basis: the buyer pays the negotiated enterprise value, then adjustments flow through for actual debt and cash at close. Orrick describes this as a negotiated term of art where cash increases proceeds and debt decreases them.
The bridge formula:
Equity Value = Enterprise Value − Net Debt − Preferred Stock − Minority Interest
Example
Two companies both sell for a $15M enterprise value. For most founder-owned private companies, preferred stock and minority interest are zero, so the bridge simplifies to EV minus net debt.
- Company A: $1M debt − $500K cash = $500K net debt → Equity Value ≈ $14.5M
- Company B: $5M debt − $200K cash = $4.8M net debt → Equity Value ≈ $10.2M
Same headline EV. A $4.3 million gap in what actually lands in the founder's pocket. Paying down debt, or building cash, before a sale process can move seven figures from the buyer's balance-sheet adjustment into your proceeds.

Key Factors That Move Your EBITDA Multiple Up or Down
Not every $5M EBITDA business gets the same multiple. Buyers price in risk, and risk shows up in a handful of predictable places.
Customer and supplier concentration. A single customer above roughly 20% of revenue tends to worry buyers: it signals fragility. Diversified, durable revenue supports a stronger multiple.
Growth rate and competitive positioning. Higher-growth sectors and defensible niches command premium pricing. Buyers pay for trajectory, not just current performance.
Management depth and founder dependency. This is often the single biggest lever for multiple expansion. Buyers ask three questions:
- Can the company operate if the founder leaves?
- Is there a real leadership team in place, or just the owner and a few loyal employees?
- Is there an actual transition plan?
A business that depends entirely on its founder is a riskier asset. Riskier assets get discounted multiples, no matter how strong the underlying numbers look.
Common Private Company Valuation Methods Beyond EBITDA Multiples
EBITDA multiples are only one input. Two other approaches help build a defensible private-company valuation:
- Discounted Cash Flow (DCF): Projects future cash flows and discounts them to present value. Especially useful for businesses with predictable, contracted revenue, where it can reduce subjectivity in pure multiple-based methods.
- Market/Comparable Transactions: Uses precedent deals in the same industry to see what similar businesses sold for, then applies those multiples to the target's financials.
Neither method works in isolation, and neither replaces solid research. At Exit Boston, senior research support covers buyer universe identification, precedent transaction research, and competitive landscape mapping so valuation conclusions rest on current market data. Used together with EBITDA multiples, these approaches give founders a clearer read on enterprise value before a sale, recapitalization, or strategic transition.
Frequently Asked Questions
How do you calculate the enterprise value of a private company?
Private company EV is typically estimated by applying an appropriate EBITDA multiple to Adjusted EBITDA, since there's no public share price to start from. The formula is EV = Adjusted EBITDA × Multiple.
How do you calculate equity value for a private company?
Equity value equals Enterprise Value minus net debt, preferred stock, and minority interest. This is the figure that reflects what actually goes to the founder at closing.
What is the best way to value a private company?
Combining an EBITDA multiple approach with comparable transaction data (and DCF analysis when appropriate) produces the most defensible valuation range. An experienced M&A advisor helps validate that range with real market data.
What is a good enterprise value to EBITDA ratio?
There's no single "good" ratio; it varies by industry, deal size, and company-specific risk. Recent middle-market data shows a range of roughly 6.4x to 8.3x depending on transaction size, with PE-sponsored deals trending toward 7.5x.
What is enterprise value for a private company?
It's the estimated total cost to acquire the business, including assumed debt, minus its cash, calculated before determining how that price gets split among shareholders. It is the full acquisition cost, separate from what the founder takes home.